Biggest Onboarding Challenges Facing UK Neobanks

The arrival of neobanks changed how we perceive banking altogether.
Opening a bank account turned into something you can do from a train platform in under ten minutes. That speed is the main catch, yet it’s also where the pressure sits. Every new account still has to pass identity checks, Anti-Money Laundering (AML) screening, and fraud controls, all while feeling instant to the person on the other end of the phone.
Get onboarding right, and a neobank wins trust, market share, and a customer who sticks around. Get it wrong, and the consequences range from lost sign-ups to regulatory fines running into eight figures.
This article looks at why onboarding is still a problem for UK neobanks, breaks down the four challenges that come up again and again, and sets out practical ways to reduce friction, manage risk, and stay compliant, without turning account opening back into a branch visit.
Why Onboarding Is Difficult for UK Neobanks
Traditional banks have relied on branch relationships and in-person ID checks for many decades. Neobanks not only don’t have that option – they don’t want it. Their entire proposition is a fully remote, app-based journey that a customer completes alone, with no human involved unless something goes wrong.
That creates a real tension. While speed is the product, every extra second spent verifying a customer is a second closer to possibly losing them. On the other hand, every second saved is a second less to catch a fraudster or money launderer.
Not to forget that today’s customers expect the convenience and immediacy that they get from the apps on their phones. At the same time, the volume of identity fraud is steadily rising, with a whopping 444,00 fraud cases recorded by Cifas, the UK’s leading fraud prevention service, in 2025 alone.
On top of that, regulators expect the same high standards of financial crime control as a 200-year-old high street bank.
It seems like neobanks are caught between a rock and a hard place – onboarding at a neobank has to be simultaneously the fastest and the most tightly controlled moment in the customer relationship.
In 2024, the Financial Conduct Authority (FCA) fined Starling Bank £28,959,426 for financial crime failings that trace directly back to how it onboarded and monitored customers. Source
The Biggest Onboarding Challenges
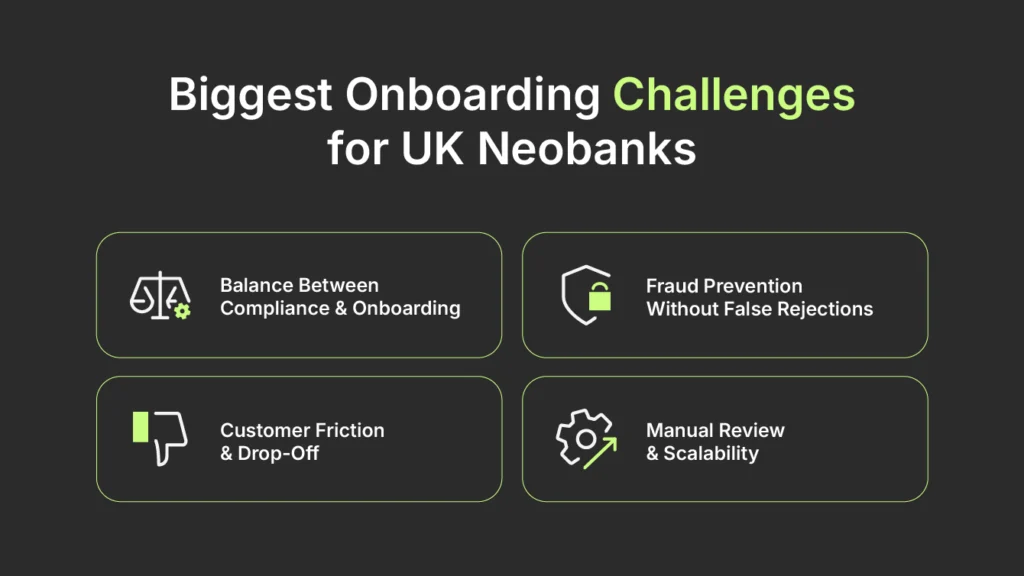
Four main problems show up again and again as UK neobanks start to grow:
- staying compliant without slowing down,
- catching fraud without punishing genuine customers,
- keeping the journey simple enough that people actually finish it, and
- handling growing application volumes without a review backlog.
Compliance Without Slowing Down Onboarding
Every UK neobank is a «relevant person» under the Money Laundering Regulations 2017, which means it must complete Customer Due Diligence (CDD) before opening an account by identifying the customer, verifying their identity from a reliable source, and understanding the purpose of the relationship.
In cases when a customer poses a higher risk of money laundering, for example, they are a Politically Exposed Person (PEP), someone linked to a high-risk jurisdiction, or anyone flagged through the bank’s own risk assessment, the UK rules (Regulation 33) require banks to apply Enhanced Due Diligence (EDD) – collect more evidence, pose questions about the source of funds, and employ tighter ongoing monitoring.
None of that is optional, and none of it is designed to be instant.
EXAMPLE: A student opening a first current account might clear standard CDD in moments. But a self-employed consultant who receives payments from three countries and lists their occupation as «director» may legitimately trigger EDD, which requires extra document requests, a call to confirm the purpose of the account, and maybe a short wait while the file is reviewed. If handled badly, the customer may feel punished for their normal working life. If handled well, they understand why the step exists and get through it without a second thought.
After conducting a multi-firm review of financial crime controls at six UK challenger banks. The FCA found that some firms had no customer risk assessment framework in place at all, and others weren’t adequately checking a customer’s income or occupation before opening an account.
That gap between quick onboarding and thorough risk assessment is exactly what regulators are watching for.
Fraud Prevention Without Too Many False Rejections
Identity fraud is now the single most common case type recorded.
Fraudsters apply for accounts using stolen or synthetic identities, submit doctored documents, and increasingly rely on AI-generated images to get past checks built around a static photo and a passport scan.
And here we stumble over an uncomfortable truth – tightening fraud controls to catch more of this also risks catching more genuine customers by mistake.
EXAMPLE: A person opening an account on their phone in a dimly lit kitchen: their face doesn’t quite match the lighting in their passport photo, glare obscures a corner of the document, and an automated system rejects them outright. They’ve done nothing wrong. The system just wasn’t confident enough to say “yes”. Multiply that by thousands of applicants a week, and a neobank can end up quietly turning away real customers in the name of stopping fraud.
Unfortunately, this is a recurrent concern. UK Finance’s Annual Fraud Report 2026 shows criminals stole £1.28 billion through payment fraud in 2025, with two-thirds of authorized push payment cases starting online,
Criminals are adapting faster than static, one-off checks can keep up, which is exactly why balancing fraud detection against false rejections is a design problem, not just a security one.
Customer Friction and Drop-Off
Every extra document upload, every failed selfie match, every «please try again» screen is a chance for a customer to just give up.
A lengthy application, unclear instructions about which documents are acceptable, or a verification step that fails for reasons the customer can’t understand – all of these lead to the same outcome: an abandoned application and a customer who opens an account with a competitor instead.
EXAMPLE: A person is trying to open an account during their lunch break. The bank asks for a selfie, then a passport photo, then proof of address, and because the address document is a mobile phone bill, which isn’t accepted, this person is asked to upload something else entirely. By the third rejection, they’ve run out of both patience and their lunch break.
Again, this is not a compliance problem, but a design problem that is damaging to the business.
The UK’s FCA addressed this problem in Consumer Duty and mandated that firms should strip out unnecessary friction that serves no purpose beyond frustrating the customer and keep «positive friction” – the deliberate pauses that genuinely protect people.
In particular, the FCA describes positive friction as short, purposeful pauses that help customers slow down and avoid harmful snap decisions, which is a useful test for whether an onboarding step is earning its place.
Manual Review and Scalability
Automated checks can’t clear every application. Some percentage will always need a human to look at a mismatched address, an unusual activity pattern, or a document that doesn’t quite scan cleanly.
And for neobanks that grow, this can turn into long queues.
For a sense of scale, the UK Financial Intelligence Unit (UKFIU) receives more than 850,000 Suspicious Activity Reports (SARs) a year from across the regulated sector. This volume shows just how much manual judgment sits behind the UK’s financial crime defenses.
EXAMPLE: A review queue that takes two minutes per case at 10,000 applications a week is a very different operational problem from one at 100,000 applications a week. Without a plan for scale, neobanks either grow the review team as fast as the customer base (which is expensive) or let the backlog grow, which is exactly the kind of gap regulators flag.
How UK Neobanks Can Improve Onboarding
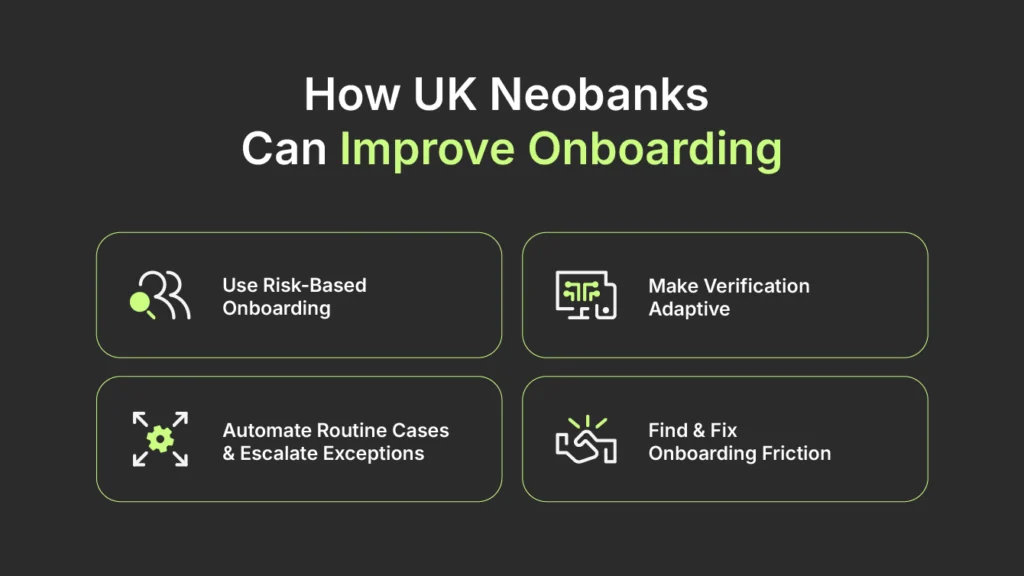
None of these challenges will disappear entirely, but they can be managed with the right design choices. Here are four approaches that can reduce friction, cut fraud losses, and keep neobanks on the right side of their regulatory obligations.
Use Risk-Based Onboarding
Not every customer needs the same level of scrutiny.
And the UK’s Money Laundering Regulations 2017 are built around exactly that principle: standard due diligence for most customers, simplified due diligence where the regulations allow it, and enhanced due diligence only where risk factors genuinely justify it.
In practice, that means:
- A UK resident opening a standard personal account, verified against a passport and a handful of basic checks – a fast path for low-risk, straightforward applications
- A business account with international directors, a customer flagged for a politically exposed connection, or an account with an unusual funding pattern – additional checks, extra steps, and higher scrutiny.
The goal isn’t to have fewer checks overall, but rather to ensure that the longer checks are applied only where they’re actually needed.
Make Verification Adaptive
A single verification method will always fail some genuine customers, such as bad lighting, an older phone camera, or a passport that’s slightly worn at the edges.
Adaptive verification means offering a fallback rather than a knee-jerk rejection. So, if a document scan fails, let the customer try a different document type; if a facial match is inconclusive, offer a short video call instead of a dead end.
This is where accessibility and fraud prevention overlap more than people expect.
For example, under the FCA’s Consumer Duty, companies should offer a sign language option for customers verifying their identity and voice control within their app for customers with dexterity difficulties.
Such built-in flexibility can save a company many customers.
Automate Routine Cases, Escalate Exceptions
The most efficient onboarding systems aren’t the ones that automate everything. They’re the ones that know exactly which cases genuinely need a person’s interference.
For example, if a customer’s name doesn’t match across documents, an address history doesn’t add up, or there’s a funding source the customer can’t explain, there should be a clear, well-tested set of escalation rules in place.
It will allow the majority of straightforward, low-risk applications to clear automatically in seconds, while triggering reviews for the cases where human judgment is actually needed.
This also directly reduces false positives. A rules engine trained to distinguish «genuinely suspicious» from «merely unusual» (for example, someone who’s just moved house, or a freelancer with irregular income) reduces the number of customers who get pushed into a review queue they never needed to be in.
Find and Fix Onboarding Friction
Yet, none of the above works without proper measurement.
You need to track:
- drop-offs by step – where exactly do people abandon the application?
- failed-check rates – which document type or check is failing most often, and why?
- time to onboard
- completion rate
- false rejection rate
All this turns onboarding from a fixed process into something that can be continuously improved.
EXAMPLE: A neobank that notices that a disproportionate number of applicants abandon at the proof-of-address stage has a specific, fixable problem. Maybe the accepted document list is too narrow, or the upload instructions are unclear.
It’s a habit the FCA itself is pushing businesses toward. As part of the Consumer Duty, the regulator expects firms to map customer journeys, test them, and act on what the data actually shows, rather than assume the process is working because no one has complained.
Bringing It Together
Onboarding is where UK fintechs / neobanks growth ambitions meet their regulatory obligations every single day.
Risk-based checks, adaptive verification, smart automation, and a genuine habit of measuring where the process breaks down can let neobanks keep onboarding fast for the customers who deserve it fast, and thorough for the cases that genuinely need it.
This combination, more than any single tool or policy, is what both customers and regulators are actually asking for.
FAQ